

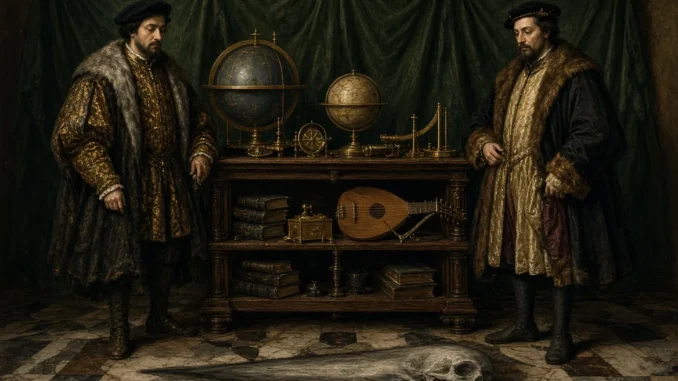
Hans Holbein the Younger was born in Augsburg around 1497 and died in London in 1543. He worked first in Basel, then entered the orbit of Henry VIII and became the most precise portraitist of the Tudor court. Without his hand the faces of the age would be unknown to us: Erasmus, and the king himself, with the broad shoulders and small eyes by which we still recognize him. Holbein’s achievement is not ornament. It is that he tells the truth about a man without stripping him of dignity.
In 1533, during his second stay in England, Holbein painted the double portrait known as “The Ambassadors.” On the left stands Jean de Dinteville, envoy of Francis I; on the right, Georges de Selve, bishop of Lavaur. Between them lie globes, instruments, books, and a lute. On the floor lies a gray smear. From the front it cannot be read. From the side it becomes a skull.
Seen from the front, the painting shows learning, rank, and order. Seen from the side, it shows what has been in the panel from the first day. Holbein did not add the smear later. He changes the angle so that the skull can be read. The lute holds a broken string: the world of the two men is full, but it is not in accord.
The American capital market this week is the same double picture. The index, seen from the front, holds the record. The long end of the curve is the skull on the floor: from the front it still looks like a smear; from the side it already reads as a skull. Credit is the lute, and the string still holds.
What the S&P 500 lets you see
On Friday the S&P 500 closed at 7,743.41, up 0.5% on the day and 1.2% on the week. From the start of the year the broad index is up about 13%. The Nasdaq Composite finished at 27,068.72, up 2.1% on the week and about 16% since January. The Dow Jones Industrial Average gained 0.9% on Friday and closed at 51,828.62. The VIX, the fear gauge, fell to 14.87. On paper this is a quiet market near a high.
Table 1. U.S. indices at the close of September 25, 2026
| Index | Friday | Week | Year to date |
|---|---|---|---|
| S&P 500 | 7,743.41 | +1.2% | +13.1% |
| Nasdaq Composite | 27,068.72 | +2.1% | +16.5% |
| Dow Jones | 51,828.62 | +0.9%* | - |
| VIX | 14.87 | down | calm |
Chart 1. The year-to-date ledger and the September ledger
| Measure | Direction | Level |
|---|---|---|
| Technology, year to date | up | +59% |
| Energy, year to date | up | +41% |
| S&P 500, year to date | up | +13% |
| Equal weight, September | down | -3% |
The yearly bar shows the engine of a narrow market. The September bar shows how narrow it has become.
*Friday’s daily gain. Source: the close of September 25, 2026.
Technology already weighs nearly 40% of the S&P 500, and three sectors hold about 61% of the index. The forward price-to-earnings ratio is about 19.4 - far from the mania of 2021, but in no sense cheap with the 10-year yield above 5%. The record requires earnings growth that outruns the new cost of capital.
The yearly ledger and the September ledger must be kept apart.
Two engines have been at work since January. Market-weight technology is up nearly 59%. Energy is up more than 40%. That is the yearly account.
September’s account is different. Eight of eleven S&P 500 sectors are down on the month, and the equal-weight index has lagged by about 3% in recent weeks while the cap-weighted index has barely moved. Last week information technology led again, up 3.1%: Microsoft added nearly 3.7% on Friday after new Copilot features, Meta posted a double-digit weekly gain around the Muse agent, and AMD entered the circle of companies worth more than a trillion dollars. The index lives on semiconductors and on the power behind them, not on the broad American firm.
Bond yields, inflation, the labor market, and credit
Table 2. Four prices for one world
| Market | What it says | Level |
|---|---|---|
| Equities | A record, narrow growth | S&P 7,743 · VIX 15 |
| Treasuries | A new discount | 10-year 5.22% · 30-year 5.52% |
| Oil | A tax on the chain | Brent $106-107 |
| Credit | Still no stress | High-yield spread ~2.8 pp |
On Monday the 10-year Treasury yield stood near 5.22%, the 30-year near 5.52%, and the 2-year climbed toward 4.91%. The 30-year yield is a level last seen in 2004; the 10-year this week touched a peak from June 2007. The 5.40% threshold is not a winter alarm. It is a week away. A print in Monday’s session is not enough. What counts is whether the yield holds after the employment report on October 2.
The Treasury market is not arguing politely with the index. It is re-pricing the cost of capital for years ahead. The dollar strengthened by nearly 2% in September: a hard currency squeezes assets outside the United States and feeds the narrow index inside it.
The yield curve is not rising on oil alone. On Wednesday the Treasury sold $70 billion of five-year notes at a bid-to-cover of 2.21 times - a 12-month low. Foreign and institutional orders took a smaller share than usual, and the auction cleared above the when-issued yield. The supply of government debt weighs on the long end together with inflation. Blame the whole curve on Hormuz and the picture lies.
Table 3. Inflation, the labor market, and supply
| Measure | Now | Note |
|---|---|---|
| CPI, August | 3.4% | The target is 2% |
| Core CPI, month | 0.3% | Firmer than expected |
| PCE / core PCE | ~3.7 / 3.3-3.4% | The Fed’s preferred gauge |
| Average hourly earnings, year | +3.1% | Below CPI |
| Payrolls, August | +162,000 | Expected ~55,000 |
| Unemployment | 4.1% | No case for a lower rate |
| Composite PMI | 58.4 | A five-year high |
| 5-year auction, Sept. 23 | 2.21× | A 12-month low |
Inflation gives grounds for that re-pricing. Consumer prices in August remained 3.4% year on year, and core CPI excluding food and energy rose 0.3% on the month. The personal-consumption-expenditures index stands near 3.7%; core PCE is about 3.3-3.4%, and the gap to the 2% target is not closed. Energy is pulling the headline again.
The labor market does not make the case for a lower rate, and it is not the source of the price impulse. In August the economy added 162,000 jobs, unemployment stayed at 4.1%, and average hourly earnings are rising 3.1% a year against consumer prices of 3.4%; real wages are not being eaten away. The acceleration comes from energy, not from labor. The flash composite purchasing-managers’ index for September jumped to 58.4, a five-year high, and the pressure is in input prices.
Credit tells a fourth story. The high-yield corporate spread is about 2.8 percentage points, and the riskier firm can still fund itself almost as cheaply as Treasuries. Gold has retreated from August peaks around $4,650-4,750 an ounce and traded near $4,200 on Monday: the metal does not confirm the index’s record; it confirms the higher discount. That is why the VIX is 15. The stress is in the price of capital, not in an expected default. The lute still plays, and the string is not broken.
The Strait of Hormuz, the oil price, and Warsh’s Fed
The war began on February 28. Until then about a fifth of the world’s crude oil and liquefied natural gas passed through the Strait of Hormuz. Flows have partly recovered: in September exports from key producers in the region returned toward 12.8 million barrels a day, and about 7.4 million appear to be moving through the strait itself. The price, however, has not returned to the old level.
On Friday Brent eased under the weight of hope for a deal. On Monday the hope shrank: President Trump rejected the Iranian proposal to reopen the strait, and Tehran did not soften its terms. Brent moved back toward $106-107 a barrel, up nearly 18% in September.
Diesel is at a historic high, and refiners have no spare capacity. The shock is no longer only in the crude barrel. It is in the fuel that enters transport and the final price.
Kevin Warsh has chaired the Federal Reserve since May. He has dropped the regular signals about future decisions and watches broad financial conditions. On September 16 the Federal Open Market Committee raised the target range by 25 basis points to 3.75-4.00%. It is the first increase since July 2023 and Warsh’s first rate move.
Twelve of eighteen participants project one more increase by year-end. The median for the end of 2026 is 4.1%. The market is pricing a majority for a move on October 28. President Trump wants a rate near 1%. The Committee raised anyway.
The strait holds energy. Energy holds the Fed. The Fed and issuance hold the discount.
The narrow index stands for as long as earnings from chips and from the power behind them grow faster than that discount. The index has not yet given way. Credit has not yet confirmed the verdict.
Why an equity record does not cancel the red flags
It is rare for an index at a record to stand beside a 30-year yield last seen in 2004 and an oil shock already measured in months. In 1999 the index held high while the Fed was tightening. In 2007 the credit spread began to move in the summer, and the broad index peaked in October. Months stood between silence in credit and the break in equities. The combination is rare. It is not proof that history has snapped.
The bull case should be stated cleanly. Semiconductor earnings are still rising, and the large platforms are still spending on capacity. The pace of that spending, however, is not given in today’s figures as either an acceleration or a slowdown. Without that measure the wager remains a thesis, not a measured bet. The high-yield spread is tight, employment supports consumption, the VIX does not signal catastrophe, and the forward multiple is not in the stratosphere. The case works until core inflation embeds lastingly in services, and until the long end compresses multiples faster than earnings rebuild them.
Table 4. Three red flags and quiet credit
| Flag | What it measures | Why it is dangerous |
|---|---|---|
| The long end | 30-year yield | It cuts multiples at once |
| Diesel in the core | Persistent energy in CPI/PCE | The Fed will not stop at one hike |
| The narrow record | 40% technology · equal weight down | It breaks when correlation returns |
| Credit | High-yield spread ~2.8 pp | It has not yet given the signal |
The book to December 31, 2026: four sleeves and three thresholds
To year-end there are three dates, not one, and four sleeves. The aim is not the last stretch of the record. The aim is that the portfolio should survive if the curve is seen from the whole room, and that it should keep enough of the narrow growth if earnings outrun the expensive long end. The absence of an alarm is not a signal to add risk. The review is after October 28, not on New Year’s Eve.
Table 5. The book to December 31 - sleeve caps
| Sleeve | Cap | Rule |
|---|---|---|
| Growth with free cash flow | ~50% | Only if it covers capital spending at today’s curve. Concentration among the platforms is accepted with the cap, not with a ban. |
| Energy hedge | 5-10% | Not cut on a Friday diplomatic dip. |
| Cash and short-dated Treasuries | ≥15-20% | Until October 28. Used to buy at a threshold. |
| Crypto assets | 3-5% | A satellite, not a pillar. |
| Protection (puts, October) | 0.5-0.8% | On the S&P 500 or the Nasdaq. Above that cost the hedge eats the income from the thesis. |
Anyone already holding more narrow growth than the target sleeve trims the surplus by as much as covers the hedge and the cash until the Federal Reserve meeting.
Table 6. Order of thresholds to year-end
| Order | Threshold | What follows |
|---|---|---|
| 1. Credit | High-yield spread > 4 pp | New risk stops. The hedge is paid for. The barrel no longer leads. |
| 2. The long end | 10-year > 5.40% after Oct. 2 | Broad market risk is expensive. The multiple is cut, not the free-cash-flow position. Monday’s 5.22% is not the signal. |
| 3. Oil | Brent < $95, if it holds | Only the energy sleeve loses its meaning as a hedge. |
A VIX at 15 is not a source of income. Leverage until October 28 punishes both mistakes. The false choice - hold everything or sell everything - is not a plan.
Conclusion
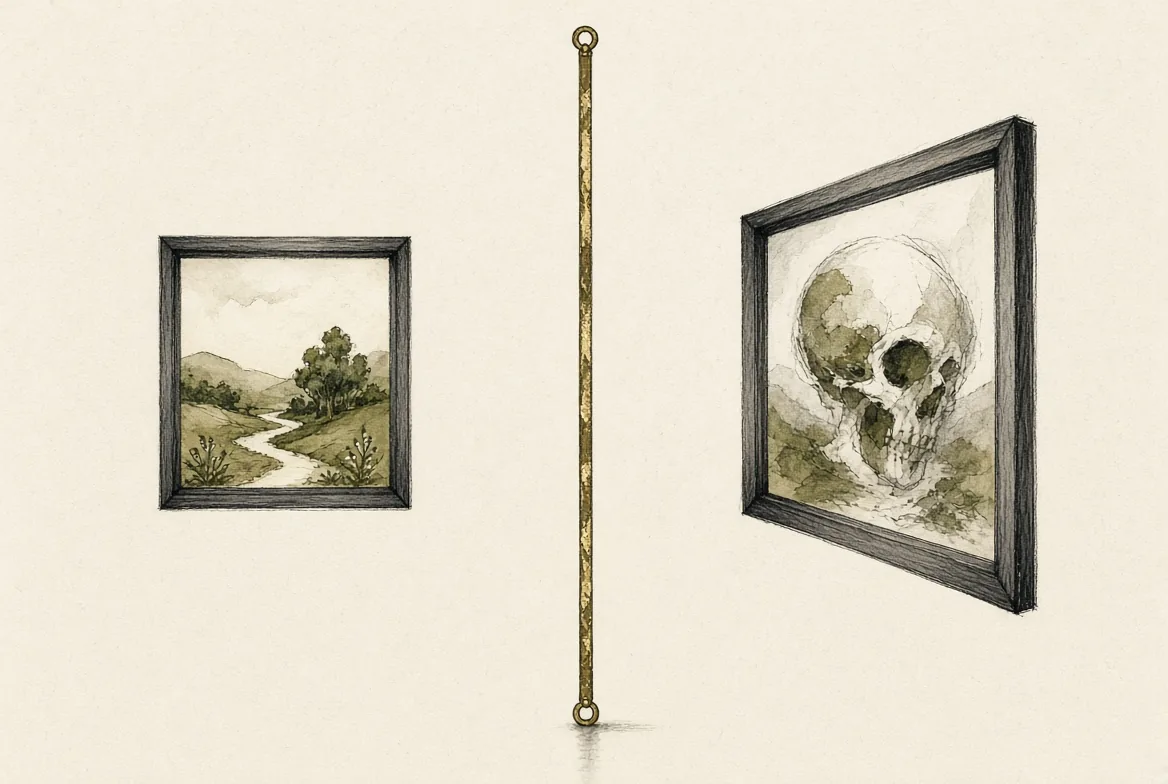
Holbein did not paint a catastrophe. He painted an angle. The skull does not cancel the globe and does not remove the lute. It says only that the frontal view is not the whole truth.
The portfolio to year-end does not take the ambassadors off the wall. It changes the place from which they are seen. The index remains in front. The long end, the barrel, and core inflation are read from the side. The thresholds are that change of stance. Until then the picture is whole, and both projections are true. The record is not proof. It is the viewpoint from the middle of the room.
Frequently asked questions on the record, the Fed, and the portfolio
How does the index hold a record with oil above $100 and the 10-year above 5%?
Because the record is not the broad market. It lives on semiconductors and on the power behind them. The equal-weight index is down in September, and the high-yield spread is still tight. For as long as earnings at the narrow end grow faster than the discount, the two projections can stand together. That does not make them one truth.
The 5.40% threshold has almost been touched. Should broad exposure be cut tomorrow morning?
No. On Monday the 10-year yield is about 5.22%, and a single touch in the session is not enough. What counts is whether the yield holds after the employment report on October 2. If after the data the yield stands above 5.40%, broad market risk is already expensive. A free-cash-flow position is not sold on the same signal.
If the strait opens next week, does the energy position stay in the book?
Only if Brent holds below $95. A Friday diplomatic sentence is not that signal. The energy sleeve is 5-10% and serves as a hedge: it is cut when there is nothing left to cover, not on hope of a deal.
Why is quiet credit not a comfort, given that spreads were tight in 2007 as well?
Because then the silence ended months before the index reached its peak. A spread near 2.8 points today shows that the corporate-debt market still does not see default. It does not show that the new discount is harmless. That is why credit is the first threshold, not a license to add portfolio risk. Above 4 percentage points, new risk-taking stops regardless of the barrel.
If no threshold is triggered by year-end, does one chase the record?
No. The absence of an alarm is not a signal to add market risk. The review is after the meeting on October 28. Until then the caps stand: about half the book in growth with free cash flow; cash and short-dated Treasuries not below 15-20%; crypto assets not above 5%; protection up to 0.8% of the book. The record, seen from the middle of the room, is not proved by adding risk on the last day.
Important notice
This article is for information and education only. It is not financial advice, an investment recommendation or professional advice of any kind. The views expressed are the author’s personal opinions and are not recommendations to buy, sell or hold securities, assets or investments. Investing involves substantial risk, including the possible loss of all capital. Past performance is not a guarantee of future results. Each reader should conduct independent research, consult a qualified financial adviser and weigh financial circumstances, risk tolerance and investment objectives before taking any decision. The author and borsite.net accept no liability for any loss arising from the use of the information in this article.